
At 57, a gym owner cashed out her life savings to open the studio she planned to retire on. She worked hard for ten years. At 67 she learned the business was worth $150,000 at most, and she had to find a plan B.
She has plenty of company. One in three small business owners has no retirement savings plan for themselves, and a common reason they give is that their savings went into the business. Nothing looks wrong along the way, either. Members pay, the doors stay open, and each year ends no closer to retirement. None of that has to happen to you.
Billy Hofacker helps gym owners with this exact problem. They make good money and keep little of it. He has spent more than 20 years in the fitness business. Today he runs Fit Profit Solutions, where he coaches gym owners on their money, and he hosts the Your Fitness Money Coach podcast. We asked him to walk us through how he fixes it.
His fix is a simple cash system. You know your numbers, you decide where every dollar goes, and you automate the moves so they happen every time. He uses it himself. He started saving for retirement late, and since the day he automated it, he hasn't had a single month where he put away less than he did in the first one. He still checks in on it, and he says you should too.
Billy joined Sequence's expert webinar series, and this was one of several things he covered:
what four numbers a gym owner should know
where a gym's profit should go
how to automate your gym's cash flow
how often to check your cash
which account to fund first
What four numbers should a gym owner know?
Billy described two gym owners. They're about the same age, they put in the same long hours, and they both have kids at home and parents getting older. More Members Mike treats every cancellation as if the business is going under. Cashflow Carl sleeps at night, and he can state four numbers about his gym in two minutes:
Revenue. Your total sales. It shows which way the gym is heading and how this year compares with last year.
Profit. What's left after expenses, ideally after you've been paid.
Net owner benefit. How much better off you are, in dollars, for owning the gym.
Cash. What's in the bank today. It's your cushion and your runway.

The four numbers, and what goes into net owner benefit.
Billy called net owner benefit the most underrated of the four, because almost nobody tracks it. He adds up four things:
what the gym pays you as an employee
the employer taxes it pays on your behalf
the gym's profit
any retirement contributions it makes for you
He allowed that you could argue about what else belongs in there. If the total rises over time, he said, you're probably in good shape.
You'll also hear that an empty account keeps an owner hungry. Billy's answer: "Not having cash in your business doesn't make you hungry. It makes you make foolish decisions." Three months of cash means the gym could go three months without a sale and still pay its bills.
Where should a gym's profit go?
Let's say the four numbers look good and there's profit at the end of the month. Most owners give that profit one job, which is to land in their own pocket. That's a real job, and Billy gave profit three more:
Taxes. On a W-2 paycheck, tax comes out before the money reaches you. A business has nobody doing that for it, so setting tax money aside on a steady schedule is your job. Ask your accountant how much.
Owner pay. A healthy gym pays you a reasonable salary and a share of the profit on top. If the salary is all you ever get, owning the gym is a lot like having a job.
Reserves. A cash buffer keeps one slow month or one unexpected expense from turning into debt. It also lets you buy when something you need goes on sale. How much to hold is debated. He said three to six months, and to call it three for now.
Growth. Money you put back into the gym. He prefers to grow "at the speed of cash" instead of on borrowed money. He called that his opinion and said a lot of factors go into it. In the financial reports he reviews, the owners carrying less debt are usually in better shape.

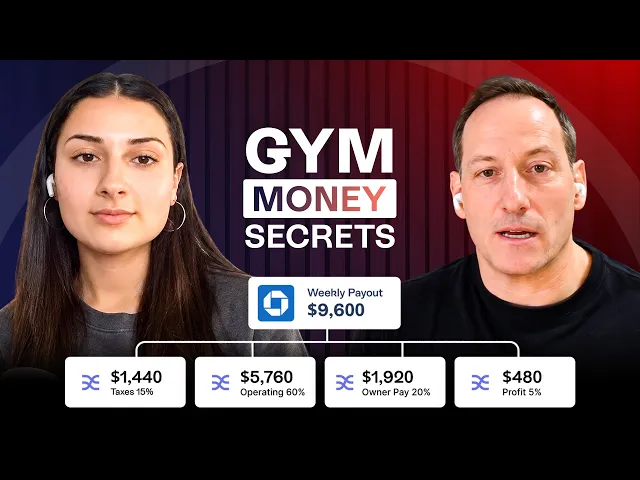
The four jobs Billy gives profit. He said the list isn't complete.
How do you automate your gym's cash flow?
The plan falls apart if each of those jobs depends on you logging in and moving money by hand. It lasts until your first busy week. Billy's fix is to make the good thing easy to do, an idea he credits to James Clear's Atomic Habits. He broke it into three steps.
Write the plan. Decide what each account gets, as a percentage or a flat amount. His examples were 30% of all revenue into an account for staff wages, and a flat $500 a month toward quarterly tax payments. Both numbers are only examples, he said.
Put the moves on a schedule. Use your bank and the tools you have so the transfers happen without you starting each one.
Review and adjust. Check the plan monthly. A new hire or a second location changes the numbers.
He put one limit on it: "You should never fully automate your finances to AI or anybody." You stay involved.
What this looks like in Sequence
After Billy's talk, Emmi Ben Tovim, our Customer Success Lead, built one of these moves live.
In Sequence, each move is an automation. You set it up with a rule that says when it runs, what it checks first and where the money goes. Emmi built hers in four steps:
Connect the business checking account you already use. Your gym's income keeps landing there.
Open an account inside Sequence for owner pay. It has its own account and routing number, so that money sits apart from what you spend.
Add an automation from checking to the owner pay account and choose when it runs: every time money arrives, or on a date. Emmi said a date can suit payroll.
Choose what it moves. She picked a percentage of each deposit.
Emmi used 30% as her example, and Billy pointed out that a lot of factors sit behind the right number. So treat these figures as an illustration. Let's say $4,200 in membership dues lands in checking. At 30%, $1,260 moves to owner pay and $2,940 stays where it is. You can change any automation whenever you want.

If you're still choosing a tool, we compared four kinds of cash flow software.
How often should you check your cash?
Once the moves happen automatically, it's tempting to stop looking. Billy said most owners wait until a bank fee shows up. He keeps two check-ins instead:
Every Friday, check your cash. Compare what's in the account with what you expected to be there. If you planned on $5,000 and it's lower, find out why. Then look ahead. Cashflow Carl knows roughly what his cash will be for the next 13 weeks. A shortfall you spot weeks out gives you choices: trim an expense, shift the timing of a bill, or collect a payment that's past due.
Once a month, spend 30 minutes on your statements. Read the profit and loss statement, the balance sheet and the cash flow statement. Then check your reserves, your goals and whether your allocations still fit.
Checking your balance all day is the other extreme, and he called it a poor use of your time.

Billy's two check-ins.
Which account should you fund first?
Billy listed six accounts a gym might keep: owner pay, taxes, debt payments, a cushion, fixed expenses, and one for everything else, like equipment. You can't fund all six at once, so he walked the group through three questions to pick one.
What's your most pressing goal?
Which account moves that goal the most?
What amount can you set aside every time without squeezing your other bills?

Billy's three questions for picking the first account.
His own example was getting out of debt. You might think owner pay is the account that matters there. He picked the cushion, because without one, every slow month or surprise bill puts you back into debt. One of the biggest keys to getting out of debt, he said, is to stop going further into it.
For the amount, he started small: 1%, or $100 a week. That $100 adds up to about $5,000 in a year.
He made one exception. If the gym isn't paying you a reasonable wage, he considers the business sick, and fixing that comes first.
If you want a full split across several accounts, our guide to Profit First for gyms shows one.
From the Q&A
Billy asked Emmi a few questions on behalf of the gym owners watching.
How is this different from the transfers my bank already offers?
Your bank lets you move money between your accounts there when you tell it to. In Sequence, an automation can also send a percentage each time a deposit lands, or top an account up to a set amount. Let's say you want owner pay to hold $4,000 on the 1st of every month. A top-up automation moves whatever it takes to get there.
How fast does the money move?
Moves between your Sequence accounts are instant. When an automation pulls money in from an outside bank, such as your current business checking, it takes 2 to 3 business days. The help center lists every transfer time.
Can business and personal accounts sit on one map?
Yes. One map can hold your personal accounts and each business you own, and each one gets its own automations.
Your next steps
Write down your four numbers: revenue, profit, net owner benefit and cash. Give yourself two minutes.
List the jobs your profit has: taxes, owner pay, reserves and growth.
Answer Billy's three questions and pick one account to fund first.
Set up one automation for an amount you can keep up. Billy's examples were 1% or $100 a week.
Check your cash every Friday, and give your statements 30 minutes once a month.
What I always recommend is to start with that one automation and watch a cycle or two go through before you add more.
If you'd like to set up Billy's playbook, use Sequence and get your finances automated today.